Proof · read live
Nothing here can be hidden, deleted or rewritten.
Four claims. For each, the mechanism behind it, what the system refuses, and where to check.
Next bank reconciliation
04:00 WAT · last run 04:00 WAT
Four figures, and where each one came from
Four claims, and the mechanism under each
Each card names the rule that enforces the claim, and where in your own account you can see it hold.
Your money is never pooled.
Every property gets its own bank account. Rent, stay income and your top-ups land there and nowhere else.
What refuses
Money cannot land against a property that has no account of its own. There is no pooled client account to fall back to.
Where to verify
- Your ledger · one account per property
- Your monthly statement · the PDF, cut per property
- This page · the clock
Nothing is deleted or edited.
A double-entry, append-only ledger. Every row is hashed against the one before it. Corrections are new rows that reverse old ones, with the author and reason.
What refuses
A posted line cannot be edited or deleted by anyone, including us. A correction is a reversal that stays on your statement.
Where to verify
- Your ledger · the reversal pair
- The anchor printed on every statement
- #verify below · the fingerprint
We check ourselves against the bank every night.
At 04:00 WAT every account is matched line by line to the bank’s statement. You see what matched and what did not.
What refuses
An unmatched line becomes a named exception and sits in suspense until somebody resolves it and says why.
Where to verify
- Your portfolio · the last run, whatever it found
- This page · the last run, and the clock to the next
No one approves their own payout.
Maker-checker. One person proposes a posting or payout; a different person approves. The rate is captured at approval and printed on the transfer with the CCI reference.
What refuses
Whoever requested a payout cannot approve it. A second member of staff must, and a payout the owner requested has no destination until staff set it from the account on file.
Where to verify
- Your payouts · every transfer, its rate, and when that rate was captured
- The transfer itself · the rate and the CCI reference printed on it
Every naira is an entry, and every entry has two sides
The row below is read from a ledger its owner has made public, with the drawer open.
the owner has published thisAppend onlyML-REV-2609
ML-REV-2609 reverses ML-EXP-2609. Both stay on the ledger, linked.
We cannot delete a mistake, so watch us answer one
ML-EXP-2609 was posted: “Borehole pump replacement, vendor invoice MLP-INV-2291”. It is still there.
It was wrong. Nobody could edit it.
ML-REV-2609 was posted against it for ₦312,000.00, in the opposite direction, with a written reason.
Both appear on the owner’s statement, linked.
Our word is checked against the bank’s, every night at 04:00
Next bank reconciliation
04:00 WAT · last run 04:00 WAT
The last run, line by line
That run had no bank lines to compare.
- Last run
- 04:00 WAT
- That run had no bank lines to compare.
- Next run
- 04:00 WAT
- The hour the scheduler runs from.
- Statements generated
- 9
- Each cut against a named ledger position.
A document you can check against us years later
MLS-LEKKI-4B-2610
- Period ending
- 31 October 2026
- Ledger anchor
- 471a104d5a32…
- Claim
- A statement you keep for years can still be checked against the ledger it came from.
- Mechanism
- Each entry is hashed from its own contents and the entry before it. A statement records the position it was cut at.
- What refuses
- Before a statement is cut the whole ledger is re-verified from the first entry. If that check fails, no statement is produced.
- Where to verify
- The anchor above and the anchor on the PDF are the same string.
The most useful thing we can show you is one we turned down
Rejected at verification
6/21
We have said no to 29% of the properties we have checked: 6 of 21.
Counted from verification rows once a verdict is reached: 6 rejected of 21 completed. 1 is still running.
The land sits inside a government acquisition that was never excised, so no Certificate of Occupancy can be issued over it and the estate holds no ratification. A buyer here would own paperwork, not property. We said no.
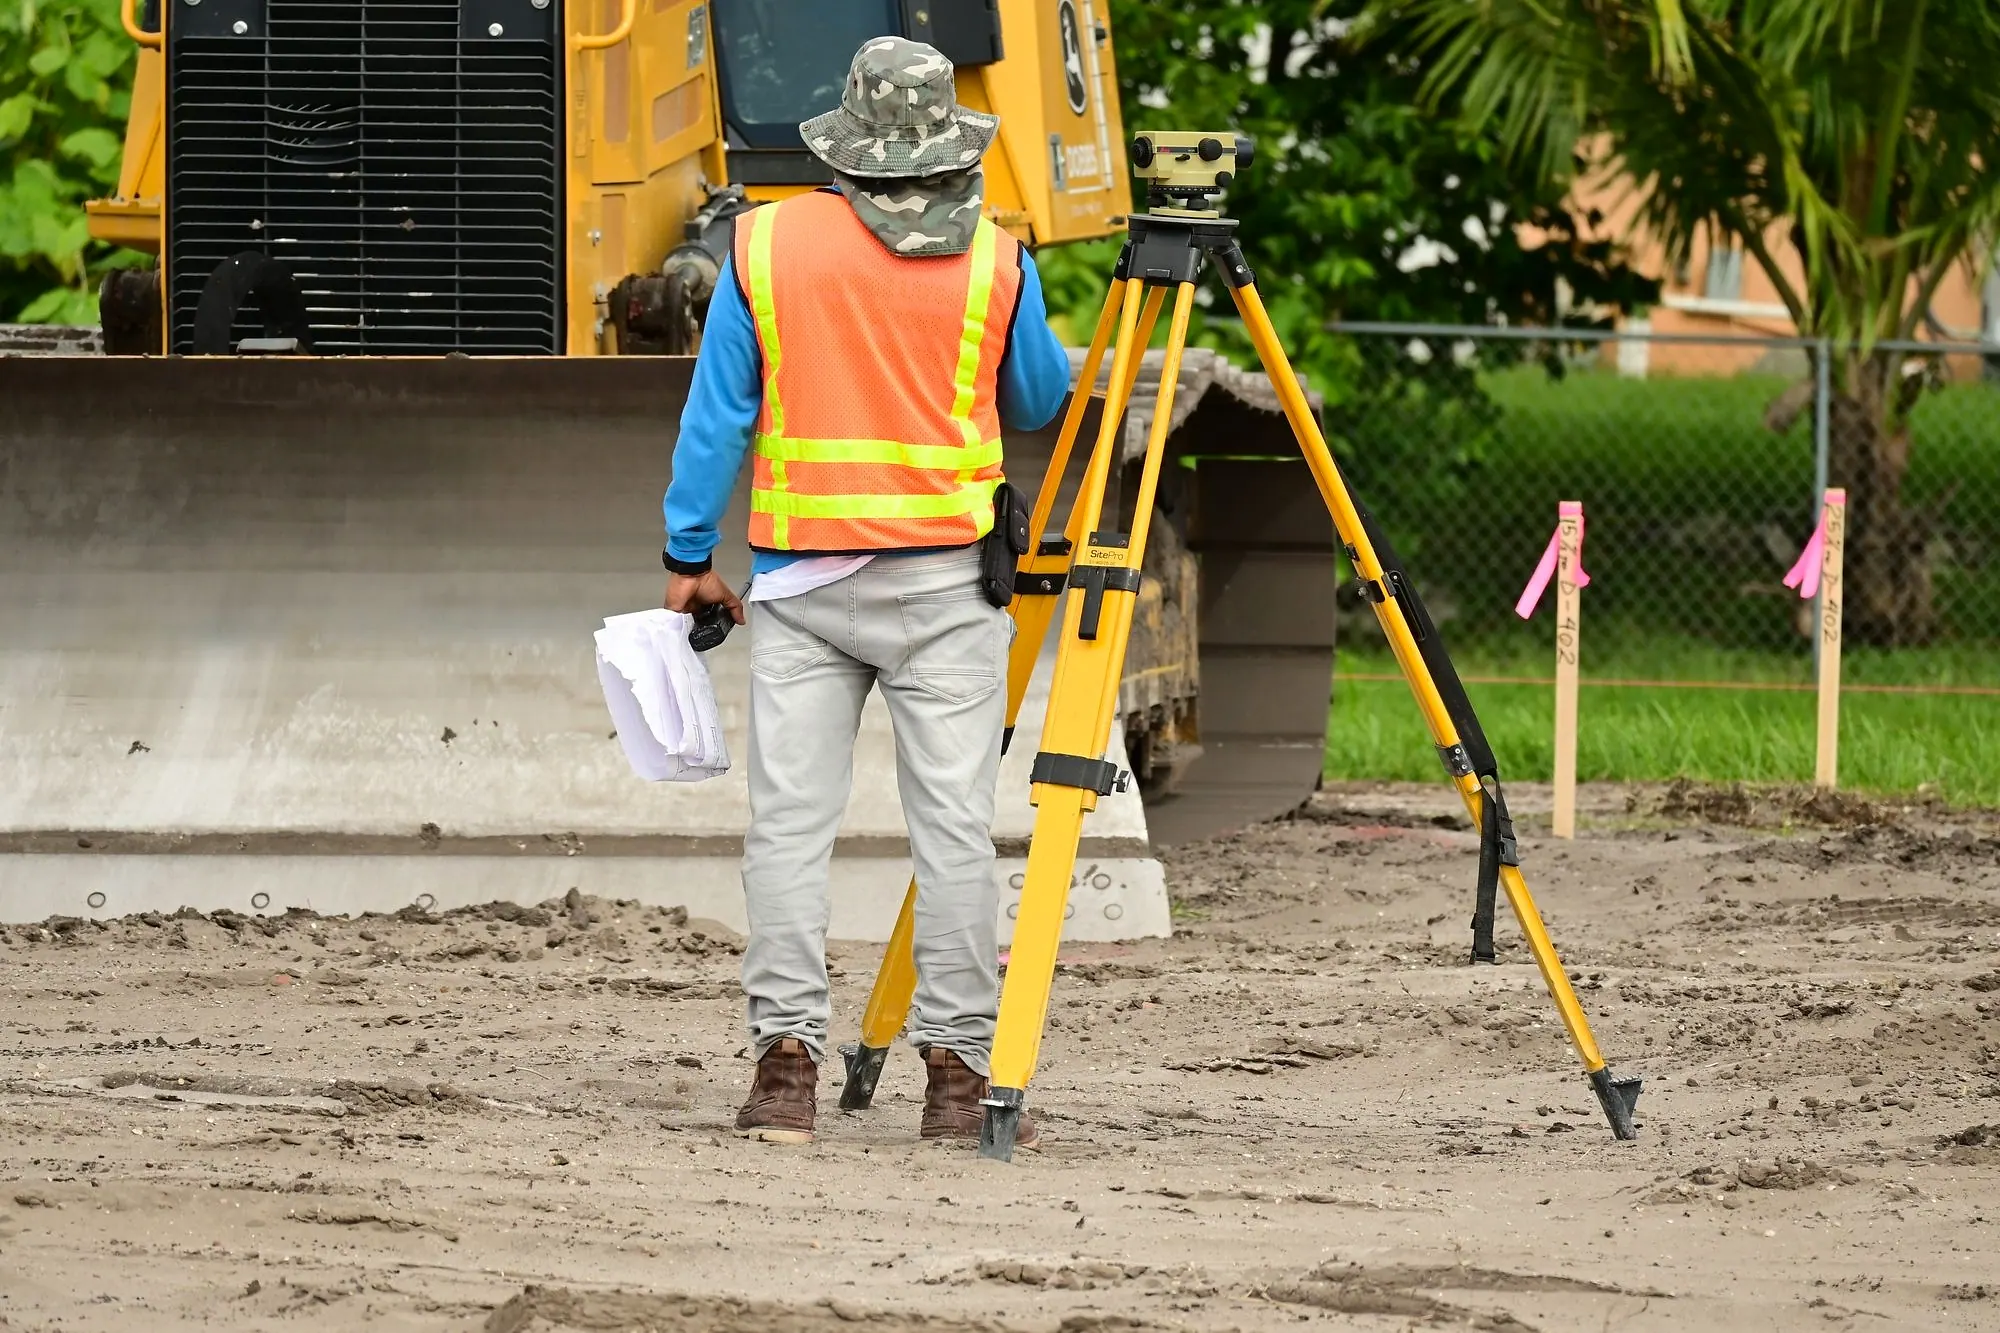
What a verification checks
- The seller is the registered proprietor at the registry
- The title instrument is registered, not merely executed
- No mortgage, caveat or lis pendens is recorded against it
- The survey matches the beacons on the ground
- Land Use Charge and ground rent are paid to date
- Building approval exists and matches what was built
- No outstanding service charge sits with the estate
- Somebody physically inspected it, and says so by name
- The access road and drainage were assessed
- Utilities are connected and the meter can transfer
- Claim
- We publish how often we say no, with the denominator in the same sentence.
- Mechanism
- The rate is derived from the counts. Under ten completed verifications it states the counts instead of a percentage.
- What refuses
- A check recorded with no note is refused. Once a verdict is reached, the checks are sealed.
- Where to verify
- The verification fee is charged whether we approve or reject.
What this does not prove
A verification is a professional opinion on the evidence available on the day, not a guarantee against a determined fraud. What we can stand behind: every check was run by a named person, and every naira that moves afterwards is posted where you can see it.
Title perfection in Lagos typically runs three to nine months.
The ask